Microsoft posted a 4QFY2026 net income of $35.8 billion, up 31% year-on-year, even as its stock swung between a 52-week low of $349.20 and a high of $553.72
NVIDIA closed at $230.10 on 4 September 2026, a split-adjusted 1,412.8% gain since December 2022
Analysts argue sitting in cash waiting for a ‘safe’ entry point risks missing the market’s strongest recovery windows
Here’s the uncomfortable truth for anyone hiding in cash right now: waiting for calm markets to buy US stocks has historically meant missing the best rallies. As of the close on 4 September 2026, Microsoft (NASDAQ: MSFT) traded at $499.70 a share, well off its 52-week high of $553.72 but still comfortably above its 52-week low of $349.20 — a spread that shows just how violently sentiment has swung this year. Yet the company’s underlying business tells a different story: 4QFY2026 net income hit $35.8 billion, up 31% year-on-year, an implemented, reported figure rather than a forecast.
Fundamentals Diverge From Stock Price Swings
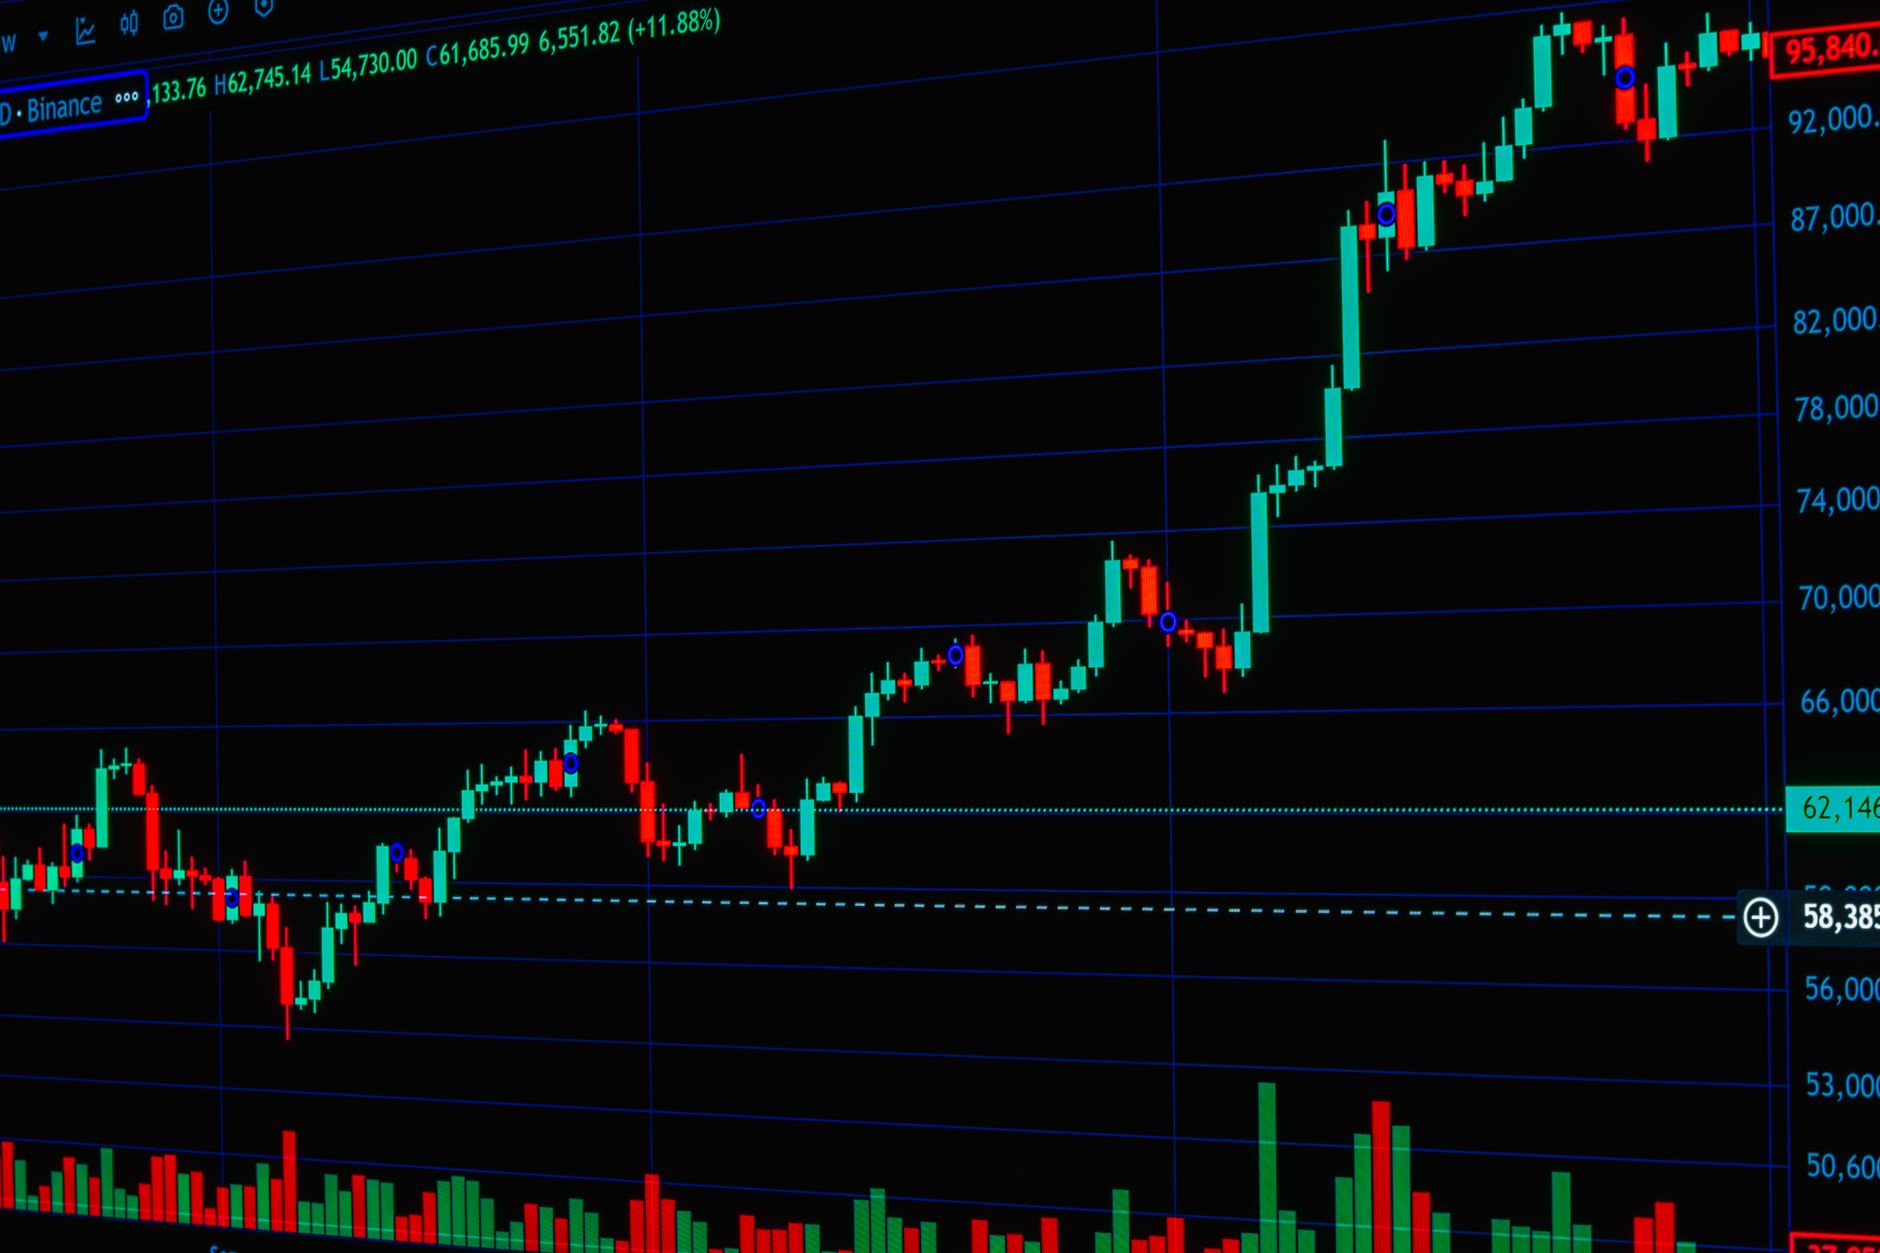
The gap between share-price noise and business performance is the whole thesis. NVIDIA (NASDAQ: NVDA), founded in 1993, didn’t become a market darling until the 30 November 2022 launch of ChatGPT ignited demand for its AI GPUs. Adjusted for its 10-for-1 stock split executed in June 2024, NVIDIA’s share price rose from $15.21 on 23 December 2022 to $48.83 by 22 December 2023 — a 221% surge in a single year, based on historical trading data. By the close on 4 September 2026, the stock sat at $230.10, marking a cumulative 1,412.8% increase since December 2022. These are realized historical price moves, not projections, though nothing guarantees the pattern repeats. Investors are also reminded that a 20% pullback doesn’t automatically signal a broken thesis, but also doesn’t guarantee a bargain — some sell-offs reflect genuine fundamental deterioration.
What This Means for Your Portfolio and Wallet
For Singapore-based investors used to dividend-heavy local blue chips, US megacaps like Alphabet (NASDAQ: GOOGL), Visa (NYSE: V), and NVIDIA offer growth exposure that simply doesn’t exist locally — access typically gained through instruments like the iShares Core S&P 500 ETF (IVV). Because many of these firms generate substantial revenue overseas, buying them also delivers indirect exposure to global growth, not just the US economy. The practical wallet impact: a diversified allocation to these names has historically smoothed the income-heavy tilt of a Singapore-only portfolio, though returns from any single stock — including NVIDIA’s outsized run — are not typical or guaranteed going forward.
Strategic Positioning & Defense Ideas
Standard hedging principles still apply here: diversify across sectors and geographies rather than concentrating in a handful of AI winners, keep a cash buffer for opportunistic buying during drawdowns, and avoid trying to time entries around volatility since dips can reflect either temporary noise or real deterioration in fundamentals. Disclaimer: This analysis is for educational and informational purposes only and should not be construed as financial or investment advice.
What to Watch Next
Watch upcoming earnings prints from Microsoft, Alphabet, and NVIDIA for confirmation that revenue and free-cash-flow growth continue supporting current valuations, and keep an eye on broader rate-driven volatility that has been rattling tech shares. Full details via thesmartinvestor.com.sg.